
Summary
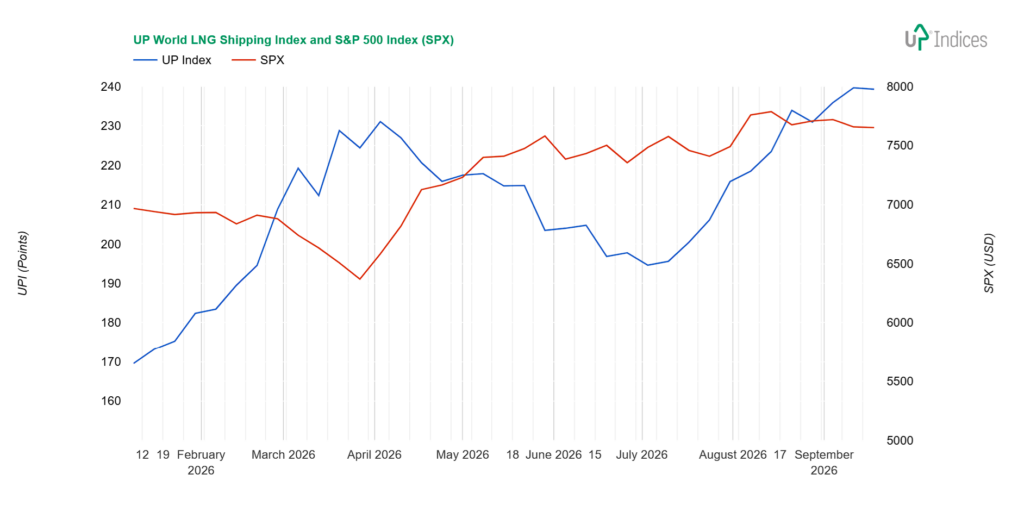
The UP World LNG Shipping Index barely moved in Week 38-2026, slipping 0.36 points (0.15%) to close at 239.27, while the S&P 500 lost 0.08%. The pause masked a split beneath the surface: decliners outnumbered gainers 8:12, and the median constituent fell 1.85%, yet the weighted index (wUPI) rose 0.6% as the heavier-weighted names — again predominantly Asian — outperformed. Trading volume ran above average. The macro backdrop was unchanged, with Asian and European gas prices firm as both regions compete for winter cargoes; European storage sits around 68.5% full, below seasonal norms, and QatarGas confirmed that the Ras Laffan refurbishment will take three years. Spot tanker rates edged up to $24,500 (Atlantic) and $26,750 (Pacific) but remain close to break-even.
Tsakos Energy Navigation led with an 8.75% gain, consolidating above its broken resistance, followed by COSCO (+5.8%) and the Japanese trio — NYK +3.14%, “K” Line +2.94% and MOL +2.75% — with NYK the only one of the three to close above its all-time-high magnetic resistance. FLEX LNG and MISC each added around 2.3%, and ADNOC Logistics & Services rose 0.68% at fresh highs. On the downside, Excelerate Energy fell 6.22% on a second rejection at $40, Pan Ocean lost 5%, and a cluster gave up around 3%: Korea Line Corporation −3.35%, BP −3.3%, Awilco LNG −3.28%, CCEC −2.96% and Nakilat −2.45%, the last still pressured by Hormuz export constraints. The short-term picture stays volatile; the long-term case — steam-vessel retirements and new liquefaction capacity — remains intact.
UPI & SPX
The UP World LNG Shipping Index, which tracks 21 listed LNG shipping companies, lost 0.36 points (0.15%), closing at 239.27 points, while the S&P 500 index lost 0.08%. The chart below illustrates the performance of both indices with weekly data.
Broader View
The UPI corrected its previous rise only very slightly; this is more of a pause than a decline. However, the ratio of rising to falling stocks was 8:12. The median change was -1.85 per cent, whilst the weighted index (wUPI) rose by 0.6 per cent. Trading volume was above average. All this indicates that the movements of the companies comprising the index were mixed — whilst most stocks fell slightly (as shown by the median), companies with greater weighting in the index tended to rise, which pulled the weighted index into positive territory. And once again, these were predominantly Asian companies.
According to Reuters’ weekly summary, the natural gas and LNG market continues to move in the same direction, with gas prices rising in both Asia and Europe as winter approaches and storage facilities need to be filled more quickly. The three key factors we have repeatedly discussed remain crucial: geopolitics, weather and time. Furthermore, QatarGas has announced that the refurbishment of the Ras Laffan facility will take three years.
“Spot global gas prices have traded at high levels over the last week as Europe and Asia continue to compete for cargoes ahead of the winter, with European storage remaining low for the time of year,” said Alex Froley, senior LNG analyst at data intelligence firm ICIS. “The recent surge in prices comes as the market realises there will likely be no solution before the winter season begins. This could drive up energy bills for businesses and households, which in time will feed into a wider economic impact on inflation and interest rates over the coming months,” he added.
South Asian demand has held firm, with Bangladesh, India and Thailand consistently issuing spot tenders, said Martin Senior, head of LNG pricing at Argus.
“The physical LNG market remained comparatively supported by ongoing concerns over Europe’s storage position and the need to secure winter supplies. European storage levels are around 68.5 per cent full, but remain significantly below historical averages and continue to underpin winter risk premiums,” said Aly Blakeway, head of Atlantic LNG at S&P Global Energy.
Spot rates for LNG tankers, according to Spark Commodities, rose slightly to $24,500 for the Atlantic and $26,750 for the Pacific, but remain low and close to the break-even point.
Constituents
Tsakos Energy Navigation (NYSE: TEN) saw the strongest growth, continuing its upward trend and, with an 8.75 per cent rise, firmly establishing itself above the broken resistance level.
COSCO Shipping Energy Transportation (SS: 600026) followed closely behind with a 5.8 per cent rise, continuing its climb towards spring price levels. This rise has brought it back into that range.
The Japanese trio gained around three per cent: specifically, NYK Line (TSE: 9101) by 3.14 per cent, “K” Line (TSE: 9107) by 2.94 per cent and Mitsui O.S.K. Lines (TSE: 9104) by 2.75 per cent.
NYK also closed above the magnetic resistance level of its all-time highs, something the other two companies failed to achieve. “K” Line thus broke through the classic resistance level but remained under the influence of the magnetic resistance, whilst MOL failed to break out of the range. It will be interesting to see whether these three titans diverge, or whether MOL catches up.
Among the rising companies, there are still two with movements of around 2.3 per cent. FLEX LNG (NYSE: FLNG) is trading within the $29.30 to $33 range, currently holding at the upper end near resistance. MISC (KLSE: 3816), following a few more volatile weeks, is attempting to return to a range with a lower boundary around 8.10. So far, it has not been successful.
The last rising company was ADNOC Logistics & Services (ADX: ADNOCLS), which rose 0.68 per cent while remaining at all-time highs.
Exmar (EBR: EXM) ended the day flat, though it too remains near this year’s highs, which are also last year’s highs. This is particularly interesting in light of the three newly acquired second-hand LNG tankers that Exmar is converting into floating infrastructure. Exmar is strengthening its position as a converter of floating LNG infrastructure — following the FSRU (Eems) and FSU (RDP/Ecopetrol), it has also received project approval from Bureau Veritas for the FLNG conversion of a membrane-type LNG carrier. Exmar thus covers the entire supply chain (im-port/storage/export) with a conversion model that gives ageing LNG tankers a second lease of life at a lower capital cost than new vessels — and with long-term contracts. The share price’s stability at its highs reflects this transition from a cyclical tanker owner to an infrastructure provider.
ALNG (OSE: ALNG) is also undergoing a business transformation, preparing its gas trading unit for market entry. Given its fleet of two tankers, we expect these to be withdrawn from spot markets and used to secure transport for trading purposes. ALNG is trading sideways, having fallen by 3.28% last week.
Excelerate Energy (NYSE: EE) is also trading within a narrow range, having fallen by 6.22 per cent. This sharp decline followed for the second time after a hard-fought climb to the $40 mark.
South Korea’s Pan Ocean (KRX: 028670) also lost five per cent. It is also trading near its all-time highs but has so far failed to break through.
A whole host of companies recorded losses of around three per cent. These range from Korea Line Corporation (KRX: 005880; -3.35 per cent), BP (NYSE: BP; -3.3 per cent), ALNG, Capital Clean Energy Carriers (NASDAQ: CCEC; -2.96%), or NAKILAT (QSE: QGTS; -2.45%).
In the case of KLC, it remains unclear whether this is the first correction in a new uptrend or, conversely, whether the previous rise was a correction of a downtrend. Given the magnitude of the movements, we believe the former is more likely.
Like many others, BP is trading near the upper end of its spring price range. However, there has been no breakout to the upside as yet, nor indeed any attempt at one.
The CCEC chart is showing some nice waves; at the moment, the wave is moving downwards. Given the truly vast area that the price has covered within this range since 2025, we can say that CCEC is moving sideways. But nothing more.
NAKILAT, hit hard by geopolitical factors, has fallen close to its lowest spring prices. Neither the trend in spot rates nor the ongoing problems with exports through the Strait of Hormuz are supporting the company’s share price.
Shell (NYSE: SHEL) underwent its first correction after breaking above the spring resistance level and fell 2.3 per cent. However, it remains above the aforementioned resistance level, which has now become support.
Chevron (NYSE: CVX)was undone by a strong resistance level, which it failed to break through when spring prices surged. Last week, it fell back below that resistance level, dropping by 2.1 per cent.
Golar LNG (NASDAQ: GLNG) continues to trade sideways, this time falling by 2.1 per cent.
Dynagas LNG Partners (NYSE: DLNG) remains difficult to read; after a spring rally that corrected the decline, it continues to move sideways, this time down 1.9 per cent. Given the concentration of prices both above and below the current level and the prolonged sideways trend, we are not drawing any further conclusions.
Crystal Ball
Qatar remains sidelined among the conflict’s losers — but the key constraint is export, not production. The damage to Ras Laffan removed around 17% of capacity (two of 14 trains), which QatarEnergy expects to take three to five years to repair. The remaining ~80% of capacity is intact and could, in principle, return to market — but the Strait of Hormuz is Qatar’s sole export route, and executives (including Shell’s) caution that even a reopening would not restore pre-war flows overnight, as high war-risk insurance continues to deter tanker returns to the Gulf. For now, this keeps a large share of Qatari volume bottled up, and US LNG exporters emerge as the clear winners. European importers were shielded from spot price increases largely because of long-term US contracts; however, these are not sufficient to replenish inventories for the winter, and European companies must return to the market despite Qatar’s continuing export restrictions. We expect most of the rising US gas production to flow toward Europe. New global LNG producers should also benefit, as energy source diversification becomes more important than ever — provided importing economies remain healthy enough to absorb higher energy costs. The outlook remains volatile, but positive in the long term. The gradual phasing out of steam vessels and the addition of new liquefaction capacity will continue to drive the sector forward.
About UPI
Established in 2020, the UP World LNG Shipping Index is a rules-based family of stock indices designed to measure the performance of publicly traded companies worldwide engaged in the maritime transportation of liquefied natural gas (LNG). This unique index comprises 21 companies and partnerships worldwide, representing more than 65% of the global LNG carrier fleet in 2020. The UP Index provides premium services, offering freemium and trial access to charts. With the Freemium plan, users can access the basic UP Index vs S&P 500 chart after completing email registration. The trial includes full access for fourteen days.
Final Note
This report primarily relies on technical analysis using weekly data. The summary section is AI-generated.
Disclosure: The author holds beneficial long positions in the shares of ALNG, FLNG, and NFE, whether through share ownership, options, or other derivatives. This report was prepared in-house and reflects our own opinions. We have received no compensation for it and have no business relationship with any company whose shares are mentioned herein.
Disclaimer: This report is provided for informational purposes only and does not constitute investment advice, nor a recommendation or solicitation to buy or sell any securities. It relies primarily on technical analysis using weekly data. Readers should conduct their own research and consult a qualified financial adviser before making any investment decisions.